Unlawful Evictions on the Rise

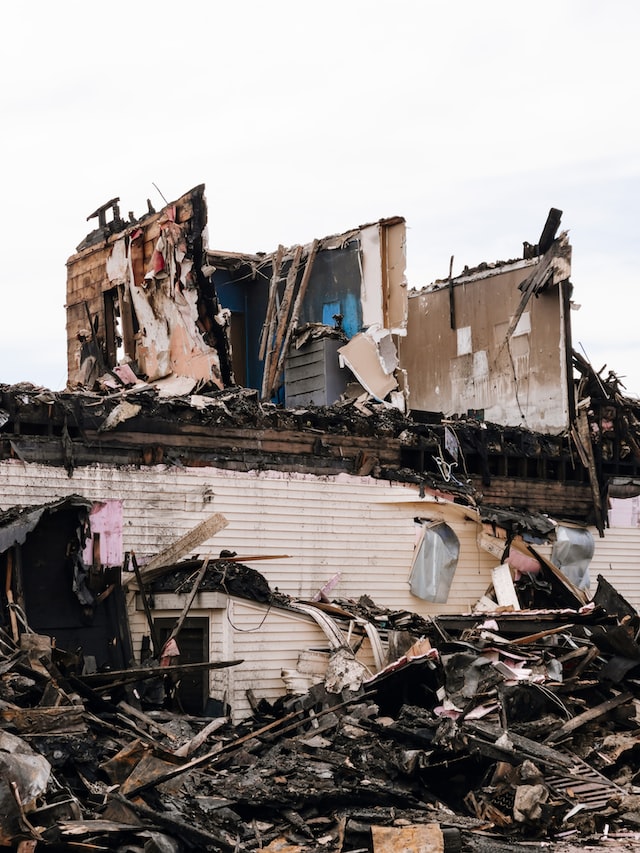
Much of the danger to tenants is being unable to pay rent, as both rental prices and cost of living continue to increase while the job market is still in recovery. However, that isn’t the only way tenants can get evicted. There are even a few ways landlords can legally evict tenants that haven’t done anything wrong. That isn’t enough for some landlords though, who are actually resorting to illegal methods of eviction instead of notifying the tenant and potentially going through the court process.

Though both are legal, the court process distinguishes at-fault and no-fault evictions. At-fault evictions are the category where failure to pay rent lies, and this category also includes various contract violations and criminal activity while on the premises. The no-fault category includes landlord’s intent to occupy the property, withdrawal from the rental market, property being deemed unfit for habitation, or landlord’s intent to demolish or substantially renovate the property. Some of these can be used misleadingly as the landlord can simply change their mind later, but the real problem is unlawful evictions. The Office of the Attorney General (OAG) is particularly concerned with the type known as self-help evictions. This includes the landlord shutting off utilities, changing locks, or removing the tenant’s personal belongings in order to force them out of the property. Landlords initiating a self-help eviction can get charged with a misdemeanor, and the sentence is either a fine or a jail term of a maximum of one year.

Photo by Mitchel Lensink on Unsplash

More: https://journal.firsttuesday.us/self-help-evictions-the-new-forbidden-fruit-for-california-landlords/86458/

Cost Effective Home Staging

Home staging is one of the best ways to garner interest in your home. Your home should look like someone lives there, otherwise buyers won’t be able to imagine themselves living there. At the same time, it shouldn’t be too personalized, otherwise it will look like a home for you rather than a home for them. Fortunately, some of the most cost effective methods of home staging are also impersonal.

While it’s certainly more cost effective if done for you rather than a buyer, updating your lighting to more energy-efficient models is sure to relieve some stress from buyers. Purchasing new furniture is expensive, but a similar effect can be achieved at much lower cost with new slipcovers and bedsheets. Even if you plan to keep them yourself, or just use them for staging, a few plants can add vibrancy to your home, particularly if they are in bloom. An important step that costs next to nothing in money, albeit a significant amount of time, is giving your entire home a thorough cleaning.

Photo by Minh Pham on Unsplash

ARM Rate Will Exceed FRM Rate by 2023

Due to the Fed increasing benchmark rates, the rates of fixed-rate mortgages (FRMs) and adjustable-rate mortgages (ARMs) are both continuing to increase at a rapid rate. The current average 30-year FRM rate is 6.70%, and it’s 5.96% for ARMs, as of Sept 30th.

It’s normal for FRM rates to be higher than ARM rates, but that may not be the case soon, because of the reasons for the rapidly increasing rates. The ARM rates are directly tied to the benchmark rates — as the benchmark rates increase, the ARM rates will also increase proportionally. While FRM rates are also increasing, it’s not directly because of the increasing benchmark rate. FRM rates are actually tied to bond market rates. However, since the FRM rates are already increasing much faster than bond market rates, they can’t sustainably go much higher, while ARM rates don’t have that restriction and are quickly catching up.

Photo by Sasun Bughdaryan on Unsplash

More: https://journal.firsttuesday.us/current-market-rates/3832/

What to Look for When Screening Buyers

Any time you are selling your home, you want to ensure that the transaction goes smoothly. The best way to do that is to pick the right buyer. Simply selling to the highest bidder may net the most profits, but that assumes the deal actually goes through. Even if it does, you may have lost time and gained headaches. Instead, make sure your buyer is qualified.

There are a few things to look for in a qualified buyer. The first is mortgage pre-approval. If your buyer is not pre-approved, they may have to back out after discovering they don’t qualify for a loan. If there’s a buyer you otherwise like but they aren’t pre-approved, you can certainly suggest getting a pre-approval before submitting an offer. You should also establish terms in the contract regarding an earnest money deposit and check that the buyer has the money ready. There are also a couple of red flags to watch out for. As cliché as it sounds, if an offer looks too good to be true, it probably is. In addition, a buyer who isn’t interested in an inspection may not be very serious.

Photo by Ali Hajian on Unsplash

San Diego Combats Its Mid-Tier Housing Problem

The housing crisis is a well-established issue and many efforts have been made, or are in the process of being made, to address it. Most of these efforts are focused on low-income housing, since it ensures that the greatest number of people are served by it. However, San Diego faces a different issue. A significant number of residents don’t qualify for affordable housing programs and are instead looking at middle-income housing. Unfortunately for the city, they aren’t able to receive federal subsidies for middle-income housing construction.

So now they’re beginning to devise a plan. The city’s Middle-Income Housing Working Group has recommended a combination of immediate actions, short-term plans, and long-term plans. Immediate steps include streamlining codes and review processes, creating a list of public land available for middle-income housing construction, and converting public facilities to mixed-use structures. Future plans include tax modifications, a public rent registry, construction loan guarantees, investing in community land trusts, and redirecting philanthropic funds to middle-income housing.

Photo by Leslie Cross on Unsplash

More: https://journal.firsttuesday.us/how-san-diego-is-addressing-its-housing-shortage/86189/

AFL-CIO Partners with Chris Gardner Foundation

The Chris Gardner Foundation is focused on helping disadvantaged youths jumpstart their careers, through their Permission to Dream program. AFL-CIO has now announced a partnership with them specifically directed at building and construction jobs. The program will help high school students, particularly students of color, to first complete their education and then secure a union apprenticeship.

If a student is selected for the program, they will first be given resources to help them in their studies as well as an instructional course in apprenticeships. Once they graduate, if they’ve maintained a certain GPA, they will be introduced to an affiliated union in the field of building and construction. The student will be placed into a paid and registered apprenticeship program. Tools and equipment are covered by a stipend, and transportation assistance is provided.

Photo by Vance Osterhout on Unsplash

More: https://aflcio.org/permissiontodream

Home Prices About to Enter Downward Cycle

Home prices fluctuate constantly, but have certainly been on an upward trend the past few years. In fact, it may not be quite as noticeable, but they’ve been trending upwards for about a decade. The difference is that the upward trend has occurred at an anomalous rate since 2019. But now, we’re starting to see hints that this isn’t going to continue. Currently, home prices are still high; however, sales volume has been dropping for the past four months, which will naturally lead to price drops.

On its own, rising home prices isn’t the problem; the issue is that they have been rising far quicker than wages. Even a period of flat home prices at their current high level would provide some slight respite to homebuyers, though of course they would benefit more from declining prices. Sellers aren’t going to be as happy in the next few years, especially if they bought recently. If they bought before 2019, they may still be able to sell at a profit, but not as much of one as if they had already sold by now. Without knowing how much prices are going to drop, there’s a risk of negative equity for homes purchased within the past three years, with the risk increasing the more recently it was purchased. If the downward cycle is particularly long or the decrease particularly steep, this could even extend to homes purchased much earlier.

Photo by Scott Webb on Unsplash

More: https://journal.firsttuesday.us/what-a-cooling-market-means-for-both-sides-of-real-estate-transactions/86063/

Home Equity Loan Facts

You may have heard of a home equity loan, but you may not know what it actually is. A home equity loan uses the accrued value of your home as collateral against a loan, and typically allows you to borrow up to 85% of the difference between the home’s value and the balance due on your mortgage. If you fail to pay back your loan, you may have to sell the house to pay it back. This is similar to a home equity line of credit (HELOC), but unlike a HELOC, a home equity loan is a one-time event with a fixed interest rate. The interest rate tends to be higher than the rate for a standard mortgage loan, but lower than rates for most credit cards. Normal regulations for mortgage loan approval apply to home equity loans as well.

A home equity loan is frequently called a second mortgage. Homeowners frequently still have some balance due when they take out a home equity loan, which means they now effectively have not one but two mortgages. In addition, the money is often used to finance the down payment on a second home. However, this isn’t the only purpose of a home equity loan. You don’t need to have a mortgage to get a home equity loan — if you don’t have one, it just means your balance due is zero, and therefore there is potentially a higher ceiling on loan amount. Furthermore, the money gained from a home equity loan doesn’t need to be used for a second home, or anything relating to homes. It’s simply your money, and can be used without restriction.

Photo by takaharu SAWA on Unsplash

A New Way to Measure Inequality

Traditionally, income inequality has been measured by something called the Gini coefficient. The Gini coefficient is measured on a scale from 0 to 1, with 0 meaning no inequality and 1 meaning a small number of people control the entirety of the wealth. While the Gini coefficient is an excellent indicator of whether or not there is inequality, it does nothing to tell us where it came from except in the case of extreme values. A new measure, the Ortega parameters, seeks to correct that.

It’s commonly thought that the wealth gap is primarily between high-income earners and low-income earners, and that the middle class is effectively nonexistent. That isn’t always the case, and the Ortega parameters can determine where this analysis is accurate and where it is not. There are two separate measures that make up the Ortega parameters: inequality between low-income and middle-to-high-income earners, and inequality between very high income earners and the rest of the population. If a population has low inequality on the first scale and high inequality on the second scale, it simply means that a small number of extremely wealthy individuals live there, but the overall inequality is actually fairly low. The Gini coefficient would not notice this nuance and just rate it as highly unequal. Determining the cause of inequality can also help to devise countermeasures: in areas with high inequality between the lower income earners and middle income earners, the solution is a higher minimum wage; in areas with a few very wealthy individuals, that is better fixed with taxes on high income earners.

Photo by Elena Mozhvilo on Unsplash

More: https://hbswk.hbs.edu/item/income-inequality-is-rising-are-we-even-measuring-it-correctly

Average Home Rentals Require Nearly $40 Per Hour Wages

The typical house in California is two bedrooms. This is traditionally considered a pretty standard starting point for homeownership. However, many individuals in California can’t even afford to rent a home of that size, let alone buy it. Between October 2020 and September 2021, the average Fair Market Rent value for a 2-bedroom home in California was measured at $2030 per month. Ideally, rent should be at most 30% of your income, meaning that in order to afford to rent a 2-bedroom home, a household would need to earn $6766 per month, or $39.03 per hour. With the average renter income being $25 per hour, a dual-income household is mandatory to be able to afford to rent a 2-bedroom house. Minimum wage workers have it even worse — at a minimum wage of $14 in California during that time period, even dual income is not enough. Minimum wage is barely higher now at $15 per hour.

So what about smaller homes? Well, unfortunately, it’s still not good enough. The average FMR for a studio — which would only be able to comfortably house one person — is $1394. But at $25 per hour, the most one person can comfortably afford is $1294 per month. At $14 per hour, minimum wage workers could only afford to pay $728 per month, which is a little over half of the rent for a studio. This is assuming full time employment, as well, and not all households have full time workers. Taking the average household income, and making sure to use only 30% of it for rent, the average household could only afford a rent of $706 per month, even less than a full time minimum wage individual.

Photo by Gio Bartlett on Unsplash

More: https://storymaps.arcgis.com/stories/94729ab1648d43b1811c1698a748c136

New Real Estate Legislation This Past August

Last month saw four new legislative changes in the field of real estate. Two bills were enrolled, AB 1738 and AB 2817. AB 1738 goes into effect in 2025, and will require builders to install electric vehicle chargers in some types of buildings. This includes multi-family dwellings, hotels and motels, and some nonresidential parking facilities. AB 2817 establishes a rental aid grant program that will provide grants directly to homeless people as well as participating landlords. SB 1126 was passed in the Senate, requiring employers to set up a retirement program or CalSavers payroll deposit savings program by the end of 2025. There was an amendment to SB 897, which increases the maximum height of an ADU from 16 feet to 25 feet.

In addition, three bills were just enrolled first day of September, AB 2221, AB 2053, and SB 869. AB 2221 includes various changes to make ADUs easier to get approved. AB 2053 requires annual regional housing reports indicating progress on meeting housing needs. SB 869 requires at least 18 hours of training for managers and assistant managers of mobile home parks.

Photo by Connor Betts on Unsplash

More: https://journal.firsttuesday.us/legislative-gossip-page/

Get Everything Prepared Before Renting Out Your Home

Renting out your home, especially for a short period, can seem like a simple way to turn a profit without much effort. However, there’s a fair bit that goes into getting the home ready to be rented out. Just like if you were selling your house, you need to make sure there’s interest, which means making a good impression on potential renters.

The easiest way to do this is by repainting your home, which is something you’d probably do if you were selling as well. It may even be more important when renting, though, especially if you aren’t going to allow your tenants to repaint. Buyers may think they’re just going to repaint anyway, so they don’t care what color the walls are. But with tenants, you want to be sure to choose neutral colors that won’t offend anyone’s aesthetic.

You should also be sure that all the legal details are worked out. You may feel the desire to skip the middleman, but that’s not a good plan. A real estate agent will help draft a lease that protects both you and the tenant. Property management companies remove much of the headache of being away from the property. Regular maintenance can often be left to property management companies. That said, if the house is not in good condition from the outset, tenants won’t be interested enough to sign a lease. Make sure to take care of repairs before you start.

Photo by krakenimages on Unsplash

Tips For Vinyl Flooring Maintenance

Vinyl has become a very popular option for flooring. It has a few important advantages going for it. Vinyl floors are both cost effective and durable, making them an attractive alternative to hardwood flooring. Many people also consider vinyl to be aesthetically pleasing. However, you can’t take advantage of that durability if you don’t know how to take care of it.

Spills and stains can become permanent if not dealt with quickly. Start by just wiping it up with clean water, then switch to a vinyl cleaning solution if you have one. For tougher stains, you can use a paste made with baking soda and water. Rub the paste into the affected area, let it sit for a few minutes, then wipe it up. If that doesn’t work either, try rubbing alcohol. As for regular maintenance, you should be sure to mop or vacuum the floor at least once per week. Wax polish isn’t necessary, but you should occasionally clean the floor with a mixture of baby oil, vinegar, and water.

Photo by Towfiqu barbhuiya on Unsplash

The Highest Crash Risk California Metros

The aftershocks of the Great Recession are already here. We’re currently in the midst of a second, undeclared recession, albeit a less severe one. The lower severity doesn’t necessarily mean lower impact, though. Government assistance is what pushed us through the Great Recession, and that’s unlikely to occur again.

A recession doesn’t have to mean a market crash, but it’s a very real possibility. Some areas are at higher risk of a crash than others. The highest risk metros are those with high loan-to-value ratios, home flipping, new residents, and rapid home price growth. In California, these metros are Riverside, Sacramento, Bakersfield, San Diego, Stockton, and Fresno. Those aren’t the only areas that may be affected, though. Market problems in any one area will also cascade to other regions.

Photo by Hans Isaacson on Unsplash

More: https://journal.firsttuesday.us/these-california-metros-risk-housing-crash-during-the-recession/85478/

Mortgage Rates Stabilizing After Sharp Rise

As a result of the Federal Reserve’s decision to increase benchmark rates, both fixed and adjustable rate mortgages have been increasing. Rates are now beginning to reach a stable point. Of course, the rates are in constant flux, but the fluctuations are starting to level out. This doesn’t mean a reversal of the recent increases; the 30-year FRM rate is levelling at somewhere around 5.5%, which is still relatively high in comparison to recent years.

What it does mean is that the uncertainty regarding rates is decreasing. With this, the popularity of ARMs will drop, as uncertainty is their primary drawback. They had experienced a surge of popularity while FRM rates were similarly unstable, since FRM rates tend to be higher than ARM rates during the same time period. This is despite the fact that ARM rates also drastically increased between July 2021 and July 2022, from 2.48% to 4.30%.

Photo by MOHD AZRIN on Unsplash

More: https://journal.firsttuesday.us/current-market-rates/3832/

Buyers Leveraging Home Defects to Negotiate Prices

In heated markets, it’s difficult for buyers to negotiate prices down, since their competition will likely be offering more. Now that the market has begun to cool, buyers are looking for ways to pay less. The answer is greater scrutiny of home defects — not to avoid purchasing defective homes, but to reduce the home’s value so they can offer less for it.

Sellers are always required to disclose any significant defects or malfunctions they are aware of in a large range of categories. These categories are walls, windows, ceilings, doors, floor, foundation, insulation, driveways, roof, sidewalks, fences, electrical systems, plumbing, and sewer or septic systems. While it can be difficult to prove that a seller was aware of a defect and the notion that it’s significant is subjective, it’s good advice for the seller to disclose anything they know. Since there’s a high chance something will have to be disclosed, buyers are jumping on the chance to leverage this to negotiate a lower sale price.

Photo by Pawel Czerwinski on Unsplash

More: https://journal.firsttuesday.us/home-defects-face-greater-scrutiny-in-2022s-cooling-market/85440/

Many Sellers Renting Instead of Repurchasing

When a homeowner sells the home they live in, their most common move is to use the proceeds to buy a replacement property, if they haven’t already done so. While it seems like homeowners would always remain homeowners, it does happen that people transition from homeownership to renting. But in most cases, the seller has decided to sell high and then rent for a short time while waiting for prices to bottom out. This is called timing the market.

This is not what’s happening now. Home prices and mortgage rates are both high, which is pricing homeowners out of their current home — and pricing 80% of them out of the market entirely. They aren’t waiting for a better time to buy; they’re simply no longer able to afford ownership. They become renters by necessity. Fortunately for people in such a predicament, it may not last too horribly long, though certainly longer than they would have wanted. It’s expected that prices will reach bottom around 2025.

Photo by Georgi Srebrev on Unsplash

More: https://journal.firsttuesday.us/home-sellers-unable-to-buy-in-2022/85079/

Consider Renting Out Your Home During Extended Vacations

Most of the time, vacations don’t last that long — a few days or maybe a few weeks. Homeowners are generally okay with leaving their homes unattended for that length of time. But what if you’re vacationing for the entire summer or winter? It’s simply not practical to leave your home vacant for three months or longer. You may want to rent out for home for the length of your vacation.

A three-month rental contract may not seem like a long time, but is actually considered a long-term contract, not a short-term contract. So it’s not any more complex of a process than any other standard rental contract. The most obvious benefit is the income generation, but there are less obvious reasons to want to keep your home occupied. Vacant homes are the primary target for burglaries, so if you have tenants in your house, you’re less likely to be a victim of crime. Tenants can notify you of any problems that arise, and also take care of regular maintenance such as mowing the lawn, though you should make sure to include this in the contract.

Photo by Alonso Reyes on Unsplash

California Mortgage Payments Now Significantly Above Rent Costs

Conventional wisdom is that it’s more financially sound to buy a house than rent, if you can afford to do so. However, this may not be entirely true anymore. While house prices and rent prices are both increasing, house prices are increasing at a much higher rate. The gap between mortgage payments and rental payments increased from $25 in April 2021 to over $800 a year later. This difference is the highest in over 20 years. Unless you’re planning to live there for over thirty years, you’re probably better off renting. Importantly, this is based on a down payment of 5%, which is significantly lower than the commonly recommended 20%, but many buyers may not be able to afford a 20% down payment.

This won’t be permanent, but it could last several years. Home price growth has already started to lessen, but interest rates are high right now. Prices aren’t expected to be at a low until around 2025. Increased construction could aid in further reducing home prices. Given that we’re seeing the the beginnings of another recession, though, that probably won’t happen until a couple years after prices bottom out. Even after a return to normality, California is still going to have a lot of renters. With many lower-income workers permanently priced out of buying, the state has consistently had the first or second lowest homeownership rate of any state, frequently swapping places with New York.

Photo by Esperanza Doronila on Unsplash

More: https://journal.firsttuesday.us/california-homeownership-priced-out-in-the-buy-vs-rent-question/84763/

What Is A Drive-By Appraisal?

In most cases, getting a mortgage loan requires a home appraisal. Usually, this is a rather long process that involves extensive analysis of a home by an appraiser, inside and out. But sometimes the process can be expedited by using a drive-by appraisal, in which the appraiser only looks at the home’s exterior. The other advantage, besides the speed, is that it’s much less invasive for any current occupants, especially if they are tenants. Of course, this is at the cost of a much less in-depth evaluation.

Also, it’s not always possible to get a drive-by appraisal. It’s essentially at the discretion of the lender whether a drive-by appraisal is allowed. If the lender wants a full investigation, they simply won’t approve the loan. That said, more and more lenders are permitting them as a result of COVID, since evaluating the interior can be risky. Lenders are also more likely to allow a drive-by appraisal for a refinance as opposed to a new loan.

Photo by Jamie Whiffen on Unsplash